












 |
|
 |
|
 |
|
 |
|
 |
|
 |
|
 |
|
 |
|
 |
|
 |
|
 |
|
 |
|
 |
|
 |
|
 |
|
Coinbaseは木曜日(2月13日)に第4四半期の収益を報告しているため、そのパフォーマンスに関する早期洞察を提供する市場データを調べます。収益のガイダンスとアナリストの見通しは株価に影響を与えますが、暗号市場データは交換の健康の主要な指標として機能します。
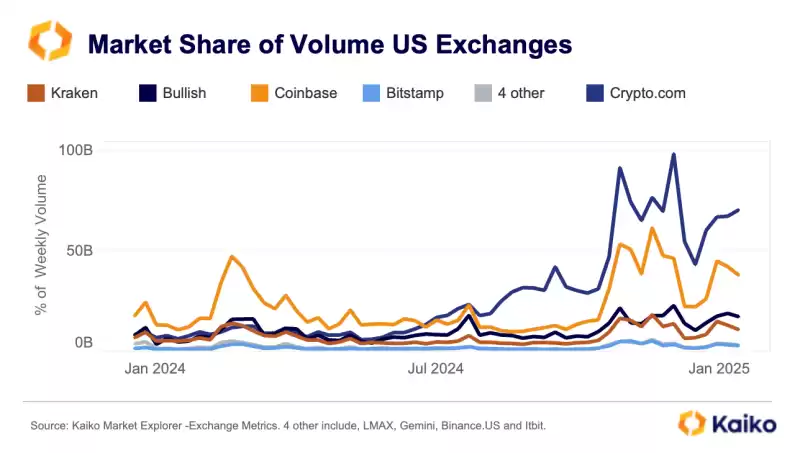
Coinbase (NASDAQ:COIN) is set to report its Q4 earnings on Thursday (Feb 13), and we examine market data offering early insights into its performance. While earnings guidance and analyst outlooks influence share prices, crypto market data serves as a leading indicator of exchange health.
Coinbase(NASDAQ:COIN)は、木曜日(2月13日)に第4四半期の収益を報告するように設定されており、そのパフォーマンスに関する早期洞察を提供する市場データを調べます。収益のガイダンスとアナリストの見通しは株価に影響を与えますが、暗号市場データは交換の健康の主要な指標として機能します。
In Q4 Coinbase weekly trade volume surged to its highest level in two years, suggesting it benefited strongly from the post-election rally. Over the past few years, Coinbase has diversified into areas beyond trading, with revenue from “subscriptions and services”—including blockchain rewards, custodial fees, and USDC interest—sharply increasing as a percentage of its total income.
第4四半期のコインベースでは、毎週の貿易量が2年で最高レベルに急増し、選挙後の集会から強く恩恵を受けたことが示唆されました。過去数年にわたり、Coinbaseは、ブロックチェーンの報酬、監護者料金、USDCの利子など、「サブスクリプションとサービス」からの収益が総収入の一部として増加することから、取引を超えた分野に多様化してきました。
However, it remains a trading platform at its core, with trading still accounting for—excluding one quarter in 2023—more than 50% of revenue.
ただし、これはその中心での取引プラットフォームのままであり、2023年に四半期を除く取引を依然として占領しているため、収益の50%以上を占めています。
Furthermore, subscriptions and services are inherently tied to activity in the underlying crypto market and do not act as diversifiers to protect against market drawdowns and trading lulls. A poor quarter for trading and price action will exacerbate losses in subscriptions and services revenue.
さらに、サブスクリプションとサービスは、基礎となる暗号市場での活動に本質的に結び付けられており、市場のドローダウンや取引の小康状態を保護するための多様化因子として機能しません。取引と価格の措置のための四半期が悪いと、サブスクリプションとサービス収益の損失が悪化します。
For example, in the third quarter of 2024 the firm’s blockchain rewards revenue fell 16% due to lower ETH and SOL prices. An understanding of staking and price trends here would have informed an investor as to the health of Coinbase’s business lines, without having to wait for the quarterly report.
たとえば、2024年の第3四半期には、ETHとSOLの価格が低いため、同社のブロックチェーン報酬収益は16%減少しました。ここでのステーキングと価格の傾向を理解することは、四半期ごとのレポートを待つ必要なく、コインベースのビジネスラインの健康に関する投資家に通知していたでしょう。
Using Kaiko’s blockchain monitoring tool we can see that net flows on Ethereum’s beacon chain fell during the fourth quarter. Coinbase which is currently the second largest ETH staking entity after Lido – is one of the largest contributors to this decline. Over the past six months the exchange’s share of the staking market has declined by 3.8%, with a net outflow of 1.29mn ETH in that period.
Kaikoのブロックチェーン監視ツールを使用して、第4四半期にEthereumのビーコンチェーンのネットフローが低下したことがわかります。現在、Lidoに次いで2番目に大きいETHステーキングエンティティであるCoinbaseは、この衰退の最大の貢献者の1つです。過去6か月間、ステーキング市場の交換の割合は3.8%減少し、その期間には1.29mn ETHの純流出がありました。
While part of the staking decrease will be offset by the higher ETH and SOL prices during the quarter, the data still suggests blockchain rewards revenue likely suffered in the fourth quarter.
四半期中のステーキングの減少の一部は、より高いETHとSOLの価格によって相殺されますが、データは、第4四半期に被害を受けた可能性が高いブロックチェーンの報酬収益を依然として示唆しています。
Meanwhile, Coinbase’s USDC-related revenue, tied to its commercial agreement with Circle, could further provide a cushion. Circle’s new partnership with Binance and record-high USDC volumes may further help offset lower income from staking (more on this in our Data Points below).
一方、CoinbaseのUSDC関連の収益は、Circleとの商業的契約に関連付けられており、さらにクッションを提供する可能性があります。 CircleとBinanceとRecord-High USDCボリュームとの新しいパートナーシップは、さらに低い収入をステーキングから相殺するのに役立つ可能性があります(これについては、以下のデータポイントで詳しく説明します)。
Still, retail traders—the highest fee payers—have not returned in force, with their share of volume shrinking to just 18%, down from 40% in 2021. Despite growth in subscriptions, this continues to weigh on transaction revenue.
それでも、最高の料金支払人である小売業者は、2021年の40%からわずか18%に減少している量のシェアを有効にして、有効に戻されていません。サブスクリプションの増加にもかかわらず、これは取引収益を比較検討し続けています。
Since peaking in mid-2023, the so-called “take rate”—a measure of the revenue generated from retail traders—has fallen to its lowest point since the first half of 2022, when the crypto market was hit hard by the collapse of Terra Luna and the crashing credit market.
2023年半ばにピークに達して以来、いわゆる「テイクレート」(小売業者から生み出された収益の尺度)は、2022年前半、暗号市場が崩壊によって激しく打撃を受けた2022年前半から最低点に低下しました。 Terra Lunaとクラッシュする信用市場。
This decline in retail-based revenue comes against the backdrop of an increasingly competitive landscape in the US with some platforms offering significant fees discounts.
この小売ベースの収益の減少は、米国のますます競争の激しい状況を背景にしており、一部のプラットフォームは大幅な料金割引を提供しています。
Although Coinbase remains one of the most liquid exchanges in the US, its fee structure – like most other platforms – favors market makers over takers and has remained relatively stable.
Coinbaseはまだ米国で最も流動的な交換の1つですが、その料金構造(他のほとんどのプラットフォームと同様)は、テイカーよりも市場メーカーを支持し、比較的安定しています。
Additionally, despite diversifying its product offerings and benefiting more from cross-product synergies, Coinbase has slowed down its listing activity due to the challenging regulatory environment in the US.
さらに、製品の提供を多様化し、生成物を横断する相乗効果からより多くの利益を得ているにもかかわらず、Coinbaseは米国の困難な規制環境のためにリスト活動を遅らせています。
The chart below shows a sharp decline in the number of actively traded pairs on both Binance.US and Coinbase following the SEC lawsuits against the two platforms in June 2023. However, this could change if the regulatory landscape improves, potentially increasing Coinbase’s appeal to retail traders.
以下のチャートは、2023年6月に2つのプラットフォームに対するSEC訴訟に続いて、Binance.USとCoinbaseの両方で活発に取引されたペアの数の急激な減少を示しています。しかし、規制の景観が改善され、コインベースの小売業に対する魅力が潜在的に増加する可能性があることを示しています。トレーダー。
Data Points
データポイント
USDC trade volume hits record high on Binance.
USDCトレードボリュームは、Binanceで記録的な高値を記録します。
Binance has become the largest USDC market, with weekly trading volumes hitting $24bn in January—49% of global USDC volume, its highest share since September 2022. This surge follows its strategic partnership with Circle in late 2024, aimed at expanding USDC adoption.
Binanceは最大のUSDC市場となり、1月には毎週の取引量が240億ドル、世界のUSDCボリュームの49%に達し、2022年9月以降の最高のシェアがあります。
In contrast, Bybit’s dominance has dropped from 38% in October to just 8% today, following its decision to reintroduce trading fees on USDC pairs and phase out USDC-settled options and futures by the end of the month.
対照的に、BYBITの優位性は、USDCペアの取引料金を再導入し、月末までにUSDCセットルのオプションと先物を段階的に廃止するという決定に続いて、10月の38%から今日の8%に減少しました。
Bullish has emerged as a strong competitor, now rivaling Binance with a 32% share of the USDC market.
強気の競争相手としてブルシュが登場しており、現在はUSDC市場の32%のシェアと競争しています。
This shift is happening alongside a broader decline in the share of newly listed USDT-quoted pairs, dropping from 77% of total listings in 2023 to below 63% in 2024 and just 50% so far in 2025—pointing to intensifying competition among stablecoins.
このシフトは、新しくリストされたUSDT引用ペアのシェアのより広範な減少とともに起こっており、2023年の総リストの77%から2024年の63%未満、2025年のこれまでのところ50%に減少しています。
Interestingly, EUR-backed trading pairs are gaining traction, potentially signaling a revival in EU markets following last year’s implementation of MiCA. For a deeper dive into EUR market trends, check out our latest report.
興味深いことに、ユーロ担保取引のペアは牽引力を獲得しており、昨年のMICAの実施に続いてEU市場の復活を示す可能性があります。 EUR市場の動向をより深く掘り下げるには、最新のレポートをご覧ください。
Altcoins liquidity increases uneven
Altcoinsの流動性は不均一になります
免責事項:info@kdj.com
提供される情報は取引に関するアドバイスではありません。 kdj.com は、この記事で提供される情報に基づいて行われた投資に対して一切の責任を負いません。暗号通貨は変動性が高いため、十分な調査を行った上で慎重に投資することを強くお勧めします。
このウェブサイトで使用されているコンテンツが著作権を侵害していると思われる場合は、直ちに当社 (info@kdj.com) までご連絡ください。速やかに削除させていただきます。


